
Why Global Funds Are Underweight on Indian Stocks: BofA Survey Explained
Bank of America's latest survey reveals global fund managers have turned underweight on Indian equities, replacing Indonesia as the least-preferred Asian market. Discover the core drivers behind this institutional shift and what it means for Indian retail investors.
Reading this article: 0s
News in 60 words
~150-word AI digest in one read
Thesis, bullets, quote & takeaway — slogan stays "60 words"
(1h)5 min read 0 0 0
Creator on ContentVerse. Building, writing, and shipping in public.
Full story
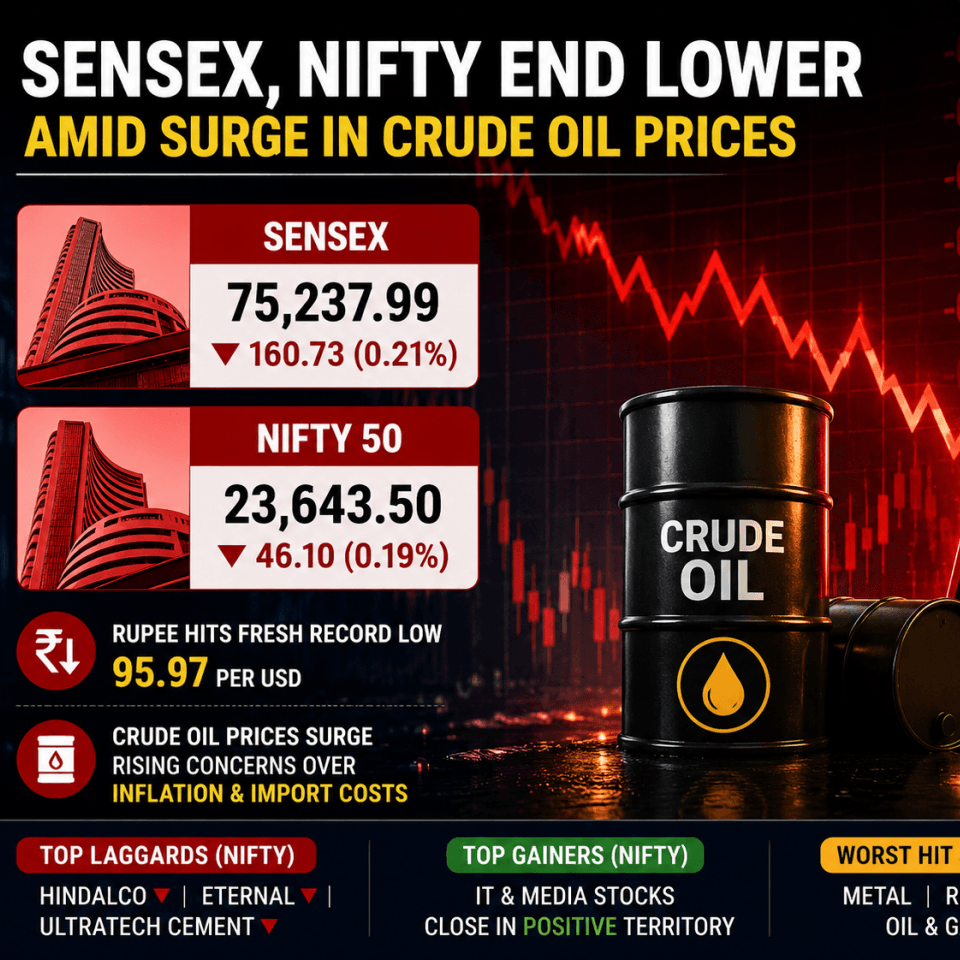
Despite India standing as the fastest-growing major economy in the world, global institutional investors are taking a step back from its stock market. Bank of America's (BofA) recent Asia Fund Manager Survey highlighted a stark sentiment shift: India has replaced Indonesia as the least-preferred stock market in the Asia-Pacific region among surveyed global fund managers.
For Indian retail investors who have watched domestic mutual funds and Systematic Investment Plans (SIPs) flood the market with record capital, this international pullback might seem baffling. Why are global funds cutting their exposure to Indian equities when headline GDP growth remains near 7%? Understanding this divergence between domestic optimism and foreign caution is essential for navigating the current market cycle.
High Valuations Leave Zero Margin for Error
The primary reason highlighted by fund managers for reducing weightage on India is valuation risk. Over the past three years, the Nifty 50 and BSE Sensex have repeatedly scaled record highs, driven by aggressive domestic buying. Consequently, Indian equities have traded at a significant valuation premium relative to other emerging markets.
- Valuation Disparity: While the MSCI Emerging Markets Index trades at a forward Price-to-Earnings (P/E) multiple of roughly 11x to 12x, the Nifty 50 has consistently hovered between 20x and 22x forward earnings.
- Small and Mid-cap Stretch: The premium is even more stretched in small and mid-cap spaces, where multiple stocks trade above 40x earnings despite moderate underlying fundamentals.
When valuations reach these elevated levels, stock prices require flawless corporate earnings execution. Any minor disappointment in quarterly results leads to sharp corrections, prompting global allocators to de-risk.
Earnings Growth Deceleration and Urban Demand Pressure
While macroeconomic indicators look robust on paper, recent corporate earnings results tell a more nuanced story. During recent quarterly reporting seasons, several key sectors—including consumer staples, retail, and automotive—showed signs of a slowdown in urban consumption growth.
- Weak Earnings Upgrades: Analysts have started downgrading earnings forecasts for several blue-chip companies rather than upgrading them.
- Government Spending Lag: Subdued government capital expenditure during early 2024 temporarily slowed down execution rates for infrastructure and capital goods firms.
Global fund managers evaluate markets on earnings momentum relative to valuation. With earnings growth moderating from 20%+ annualized rates down to single digits or low teens for many benchmark components, foreign money managers find it hard to justify India's premium pricing.
The Great Rotation Toward China and Other Asian Markets
Global portfolio management is inherently relative. An investor decision to go underweight on India is often driven by attractive opportunities elsewhere in the region.
- China's Policy Stimulus: Unprecedented monetary easing and stimulus packages announced by the People's Bank of China (PBoC) led many global funds to reallocate capital back into beat-down Chinese equities trading at single-digit P/E multiples.
- North Asian Tech Exposure: Fund managers seeking growth have actively rotated funds toward Taiwan and South Korea to capitalize on the global artificial intelligence hardware boom.
- Japan's Governance Reforms: Tokyo's ongoing corporate governance reforms have drawn massive institutional flows away from other emerging allocations.
As global funds sold off high-valuation Indian shares to fund cheaper, high-beta bets in China and North Asia, Foreign Portfolio Investor (FPI) outflows from Indian secondary markets spiked significantly.
The Divergence Between Foreign and Domestic Liquidity
One unique characteristic of the current market structure is the stark tug-of-war between Foreign Portfolio Investors (FPIs) and Domestic Institutional Investors (DIIs).
- FPI Net Selling: Foreign investors have withdrawn tens of thousands of crores from Indian secondary markets in heavy selling sprees.
- DII Inflow Cushion: Indian retail investors, channelizing over ₹23,000 crore monthly through SIPs alongside domestic pension and insurance funds, have absorbed the foreign dumping.
While domestic liquidity prevents a market crash, it creates a market cap where index returns stall while individual stock volatility remains high. Foreign funds are also participating selectively—often bidding heavily in mega Initial Public Offerings (IPOs) like Hyundai Motor India or Swiggy while selling down existing secondary holdings.
What This Means for Indian Retail Investors
For retail investors on Dalal Street, an underweight stance from global fund managers is not a reason to panic, but a signal to adjust expectations and refine strategies.
- Focus on Quality and Fair Value: Broad-market momentum where every stock rises is over. Prioritize companies with strong balance sheets, reasonable valuations, and steady cash flows.
- Staggered Investments: Maintain long-term SIP discipline rather than committing large lump sums into broad-market index funds during valuation peaks.
- Sectoral Selectivity: Sectors like private banking, pharmaceuticals, and technology—where valuations are closer to historical averages—may offer better risk-reward profiles than over-extended railways, defense, or PSU stocks.
Frequently Asked Questions
Why are global fund managers underweight on Indian stocks despite strong GDP growth?
While India's economic fundamentals are strong, global investors view the stock market as overvalued compared to historical averages and peer emerging markets like China or Korea, offering less immediate upside risk-reward.
Is the foreign institutional investor (FPI) selling permanent?
No. FPI allocation moves in cycles. Once Indian stock valuations adjust to reasonable levels or corporate earnings growth accelerates again, global capital tends to return due to India's long-term structural growth story.
How should retail investors respond to the BofA survey findings?
Retail investors should avoid chasing speculative momentum, stick to systematic asset allocation, focus on quality businesses with reasonable valuations, and keep long-term investment horizons intact.
Conclusion
The BofA survey highlights a classic market reality: even the best long-term economic growth story can become an unattractive short-term trade if valuations run too far ahead of earnings. While domestic retail inflows provide a strong floor for Indian equities, foreign institutional investors are choosing to wait for better price entry points or faster earnings growth before turning overweight again. Smart investors will use this phase to review portfolio quality, manage liquidity, and focus on long-term value creation.
Disclaimer: This is educational content, not financial advice.
Support creators
If you found this market breakdown insightful, consider tipping the author on ContentVerse India to support independent financial journalism.
Was this helpful?
Your feedback helps us improve content for everyone.
Liked this piece?
Tip Dhananjay for the work
100% goes to the creator. Send a one-time tip in rupees and back the writing you love.
Dhananjay Singh
3 followers · 99 blogs
Published 19 Sept 2026
Creator on ContentVerse. Building, writing, and shipping in public.
Reviewed by the ContentVerse India editorial team. Educational pages are not personalised advice.
View full profile3 followers
Discussion